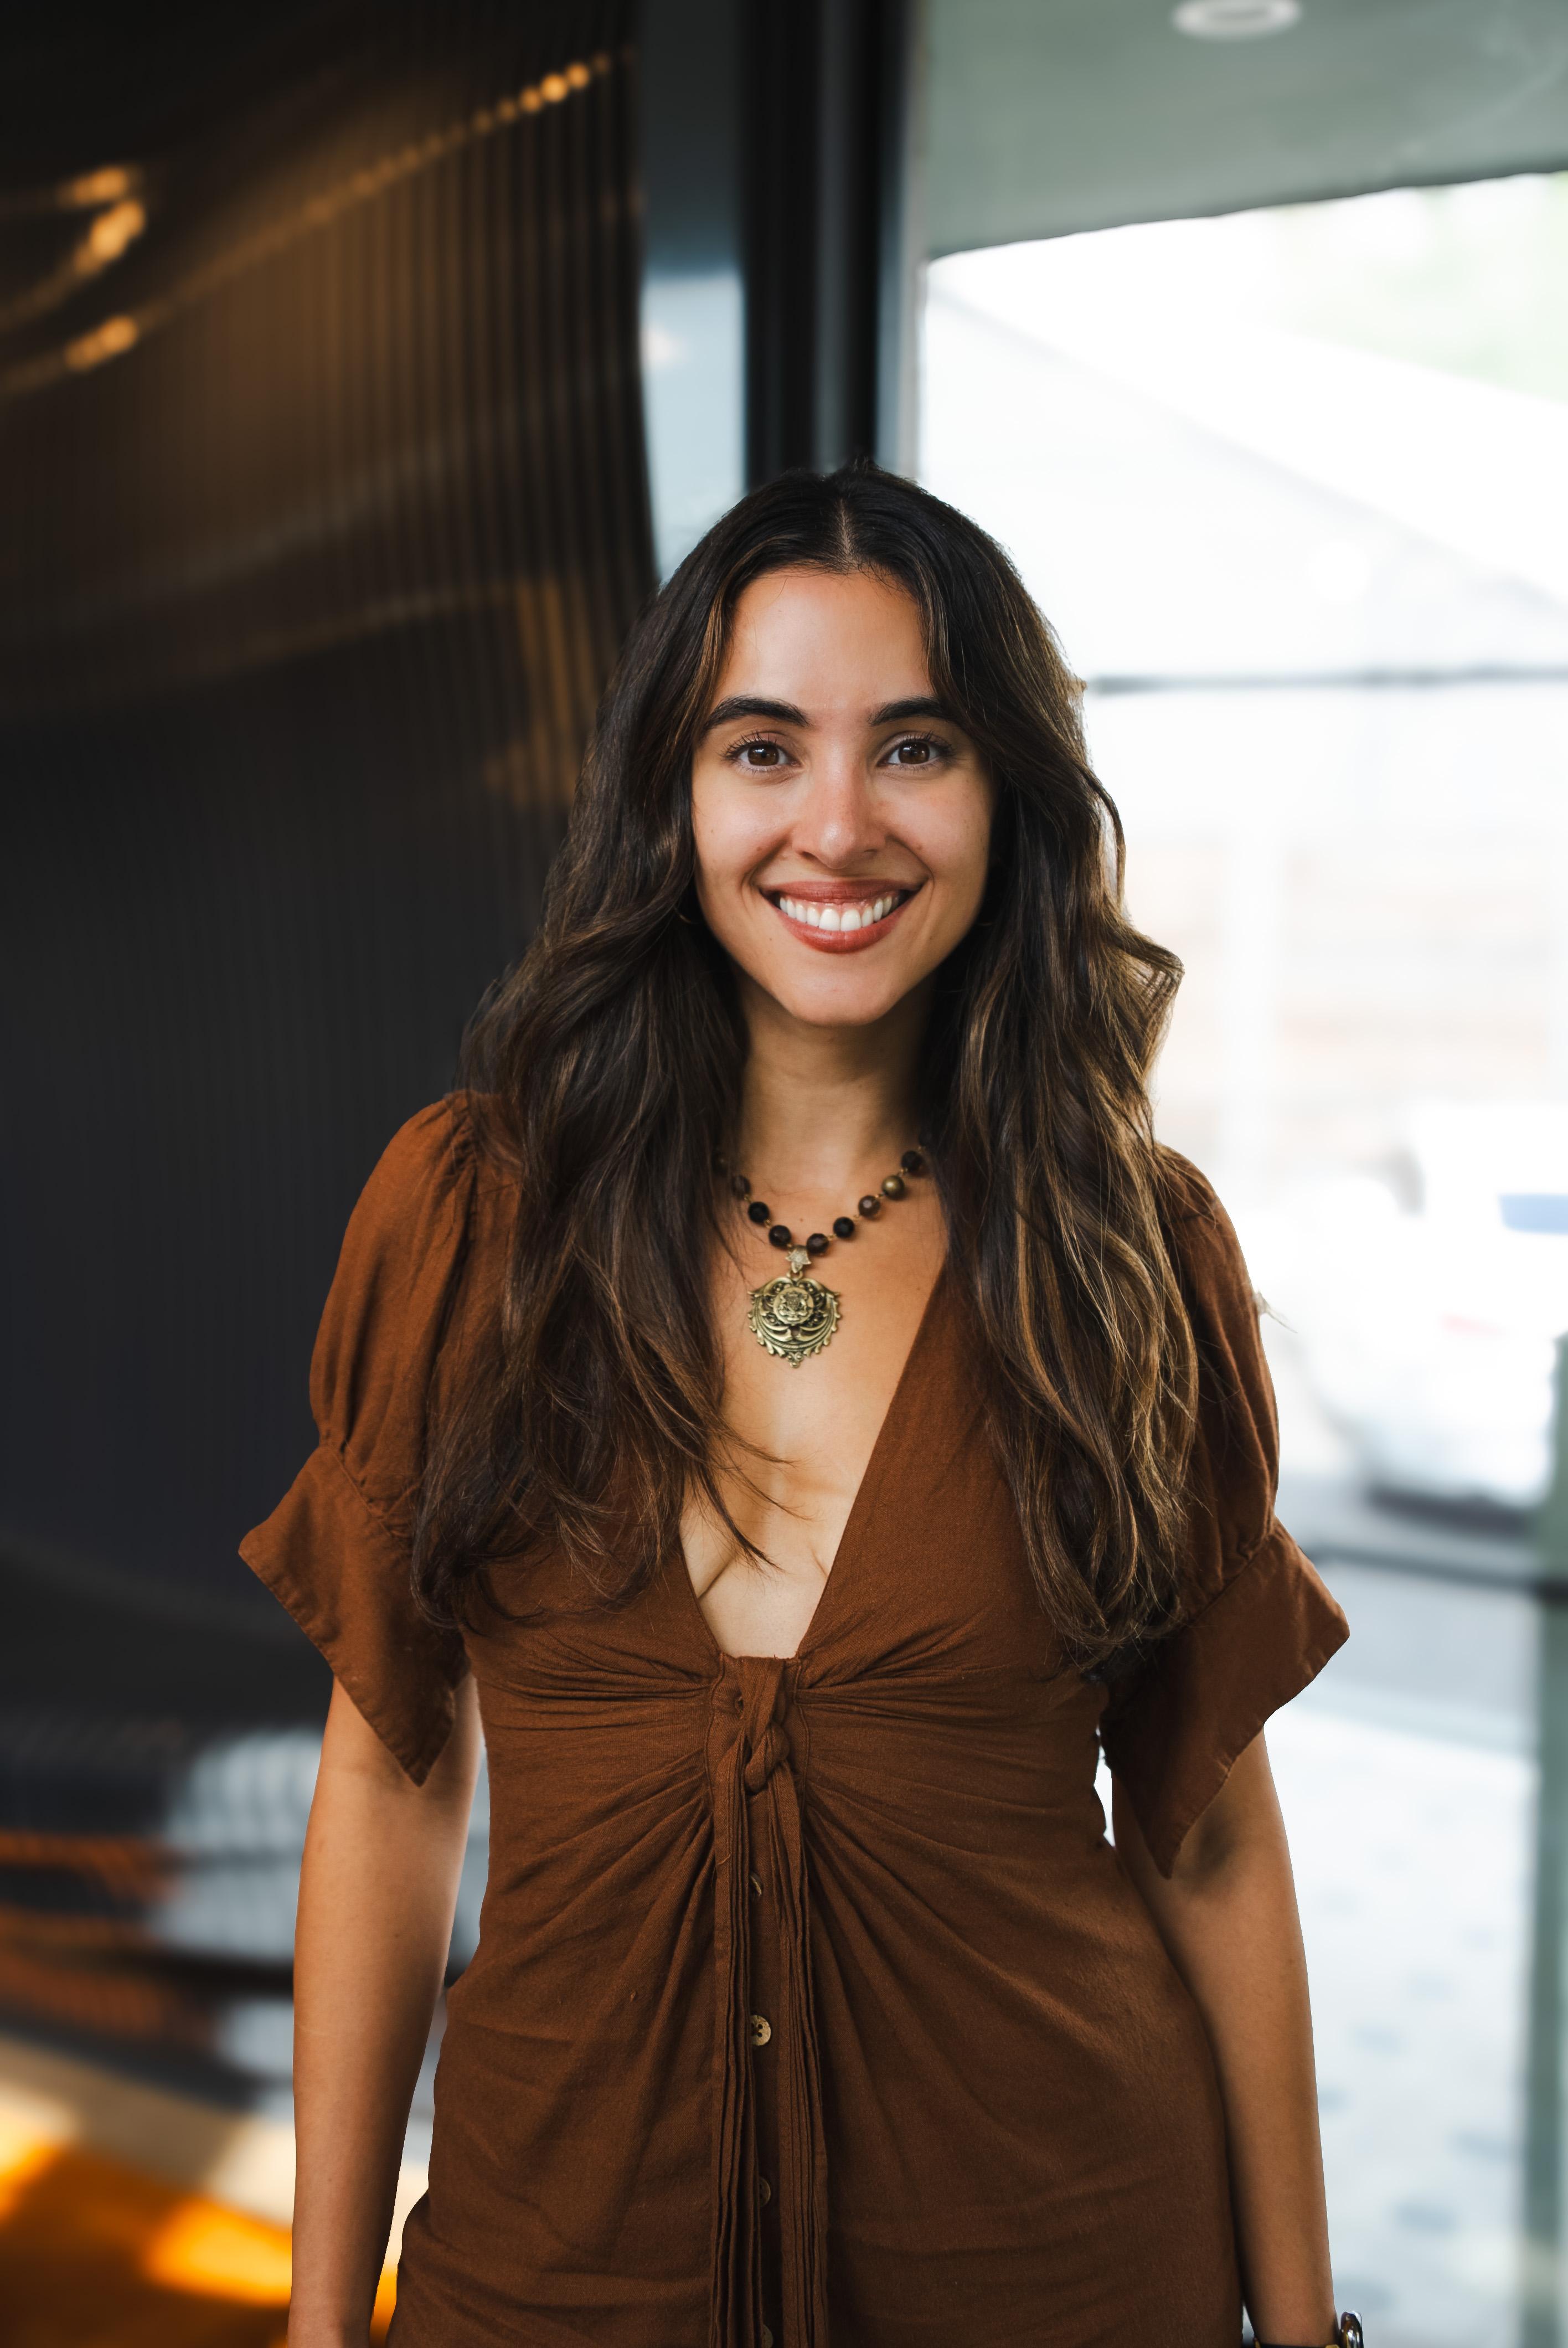
Jennifer Ferrara · NMLS #2781982
Loans built
like home.
Anybody can hand you a rate. We build the strategy around your situation, your financials, your lifestyle, and whether the offer you are about to write actually works.
We structure every loan for precision from day one, so nothing gets discovered late, and we work to make sure nothing on our end holds up your closing date. Let’s find the right fit for you and get this done.
Jennifer
Mortgage broker serving Hays County and Austin, TX
By the numbers
I learned this business from the other side of the table.
There’s a difference between understanding one piece of the transaction and understanding how the pieces fit together. Very few people have sat in both chairs, and that experience creates a more strategic approach, helping clients save time, reduce costs, and make smarter decisions.
- 14
- Years in real estateLicensed at 18 in New York City, 6 of them here in Central Texas.
- $65M+
- In real estate transactions closed120+ transactions. Real estate production, not lending volume.
- Top 1.5%
- Of agents nationallyRanked on production, not tenure.
- 40+
- Wholesale lenders shoppedOne loan, run across a panel, not one bank’s single answer.
Find your loan path
Buying your first home
A first home with a conventional or FHA loan, explained step by step.
- You’ve never done this before and want it actually explained
- You’re not sure if 3% or 5% down makes more sense yet
Your Loan Journey
Four steps, and the first one costs you nothing.
Tell me what’s actually going on
No application yet, no credit pull, nothing that shows up as an inquiry on your report. Just the real situation, including the parts that feel like they might be a problem.
I build your strategy before you shop
Before you write an offer, I build your plan: debt and payment structure optimized, every program you qualify for identified, and real tax and insurance numbers pulled for your target areas.
You see the real options side by side
Every loan program that fits, laid out with what it costs up front and every month after. I will guide you through the options. The decision stays yours.
We close it, and I stay on it
One point of contact from application to the closing table. I build the timeline backward from your contract date and stay ahead of underwriting and appraisal so we close on schedule. If something changes along the way, you are hearing it from me, not finding out at the end.
Awesome thanks!
Stephen Hsu
Google review · · Read it on Google
I worked with Jennifer Ferrara at Nook Lending on an FHA loan for first-time homebuyers in the Austin area. My clients were understandably nervous about the process, but Jennifer explained each step clearly and proactively, often answering questions before they even knew to ask. As their real estate agent, I never had to play translator between my buyers and the lender. Communication was consistent, the financing process stayed on track, and we closed without a hitch. Most importantly, my clients arrived at the closing table feeling confident and truly understanding their loan. I highly recommend Jennifer and Nook Lending to buyers looking for a knowledgeable, responsive, and reliable mortgage professional.
Latreacia Mays
Referring real estate agent · · Read it on Google
What could this look like?
Type in a price, a down payment, and a rate you want to test. Nothing here is a quote, and none of it touches your credit. It is a planning tool, so move the numbers around and see what changes.
This is a number you choose for illustration. It is not a rate offered to you, not a quote, and not tied to any live pricing.
Loan term
Estimated monthly payment
$2,824
on a $332,500 loan
- Principal and interest
- $2,102
- Property taxes
- $522
- Homeowners insurance
- $200
Mortgage insurance is not included, and it applies on most loans under 20 percent down. The quiz below is the fastest way to see which loan type actually fits these numbers.
Estimate for planning purposes only. This calculator uses figures you enter yourself and does not reflect an actual rate, payment, or offer available to you. It is not a quote, a pre-qualification, or an application. This is not a commitment to lend. All loans are subject to credit approval, income and property verification. Rates, terms, and programs are subject to change without notice. Nook Lending is powered by MPA Home Loans. Jennifer Ferrara, Loan Officer, NMLS #2781982. MPA Home Loans NMLS #2778343. Equal Housing Opportunity. NMLS Consumer Access
Which door is yours?
These eight come up most. Every one has its own page with what it takes, who it fits, and the questions people actually ask. I work with 14 programs in all, so if yours is not here, it exists.
- First-Time HomebuyerAnyone buying their first home, or buying again after several years away from ownership.First-Time Homebuyer
- ConventionalBuyers with solid credit who want the lowest long-run cost and want mortgage insurance to eventually go away.Conventional
- FHABuyers rebuilding credit, carrying more debt than conventional allows, or working with a small down payment.FHA
- Non-QMAnyone whose income is real and provable but does not fit a standard W2 underwriting box.
- Self-Employed / Bank Statement1099 contractors, business owners, and anyone whose tax return understates what they really earn.
- DSCR InvestorInvestors buying rentals, and anyone whose personal debt-to-income ratio is blocking the next purchase.
- BridgeMove-up buyers who need their equity freed up before their current home sells.
- JumboBuyers in the higher price bands, often self-employed professionals and move-up buyers.
- Already have an estimate from another lender?Send me the numbers from your Loan Estimate and I will compare it with you line by line, at no cost. A real comparison with real numbers from me starts with an application.
Not sure which one fits?
Four questions, no typing, and nothing that touches your credit. It will point you at the right starting place.
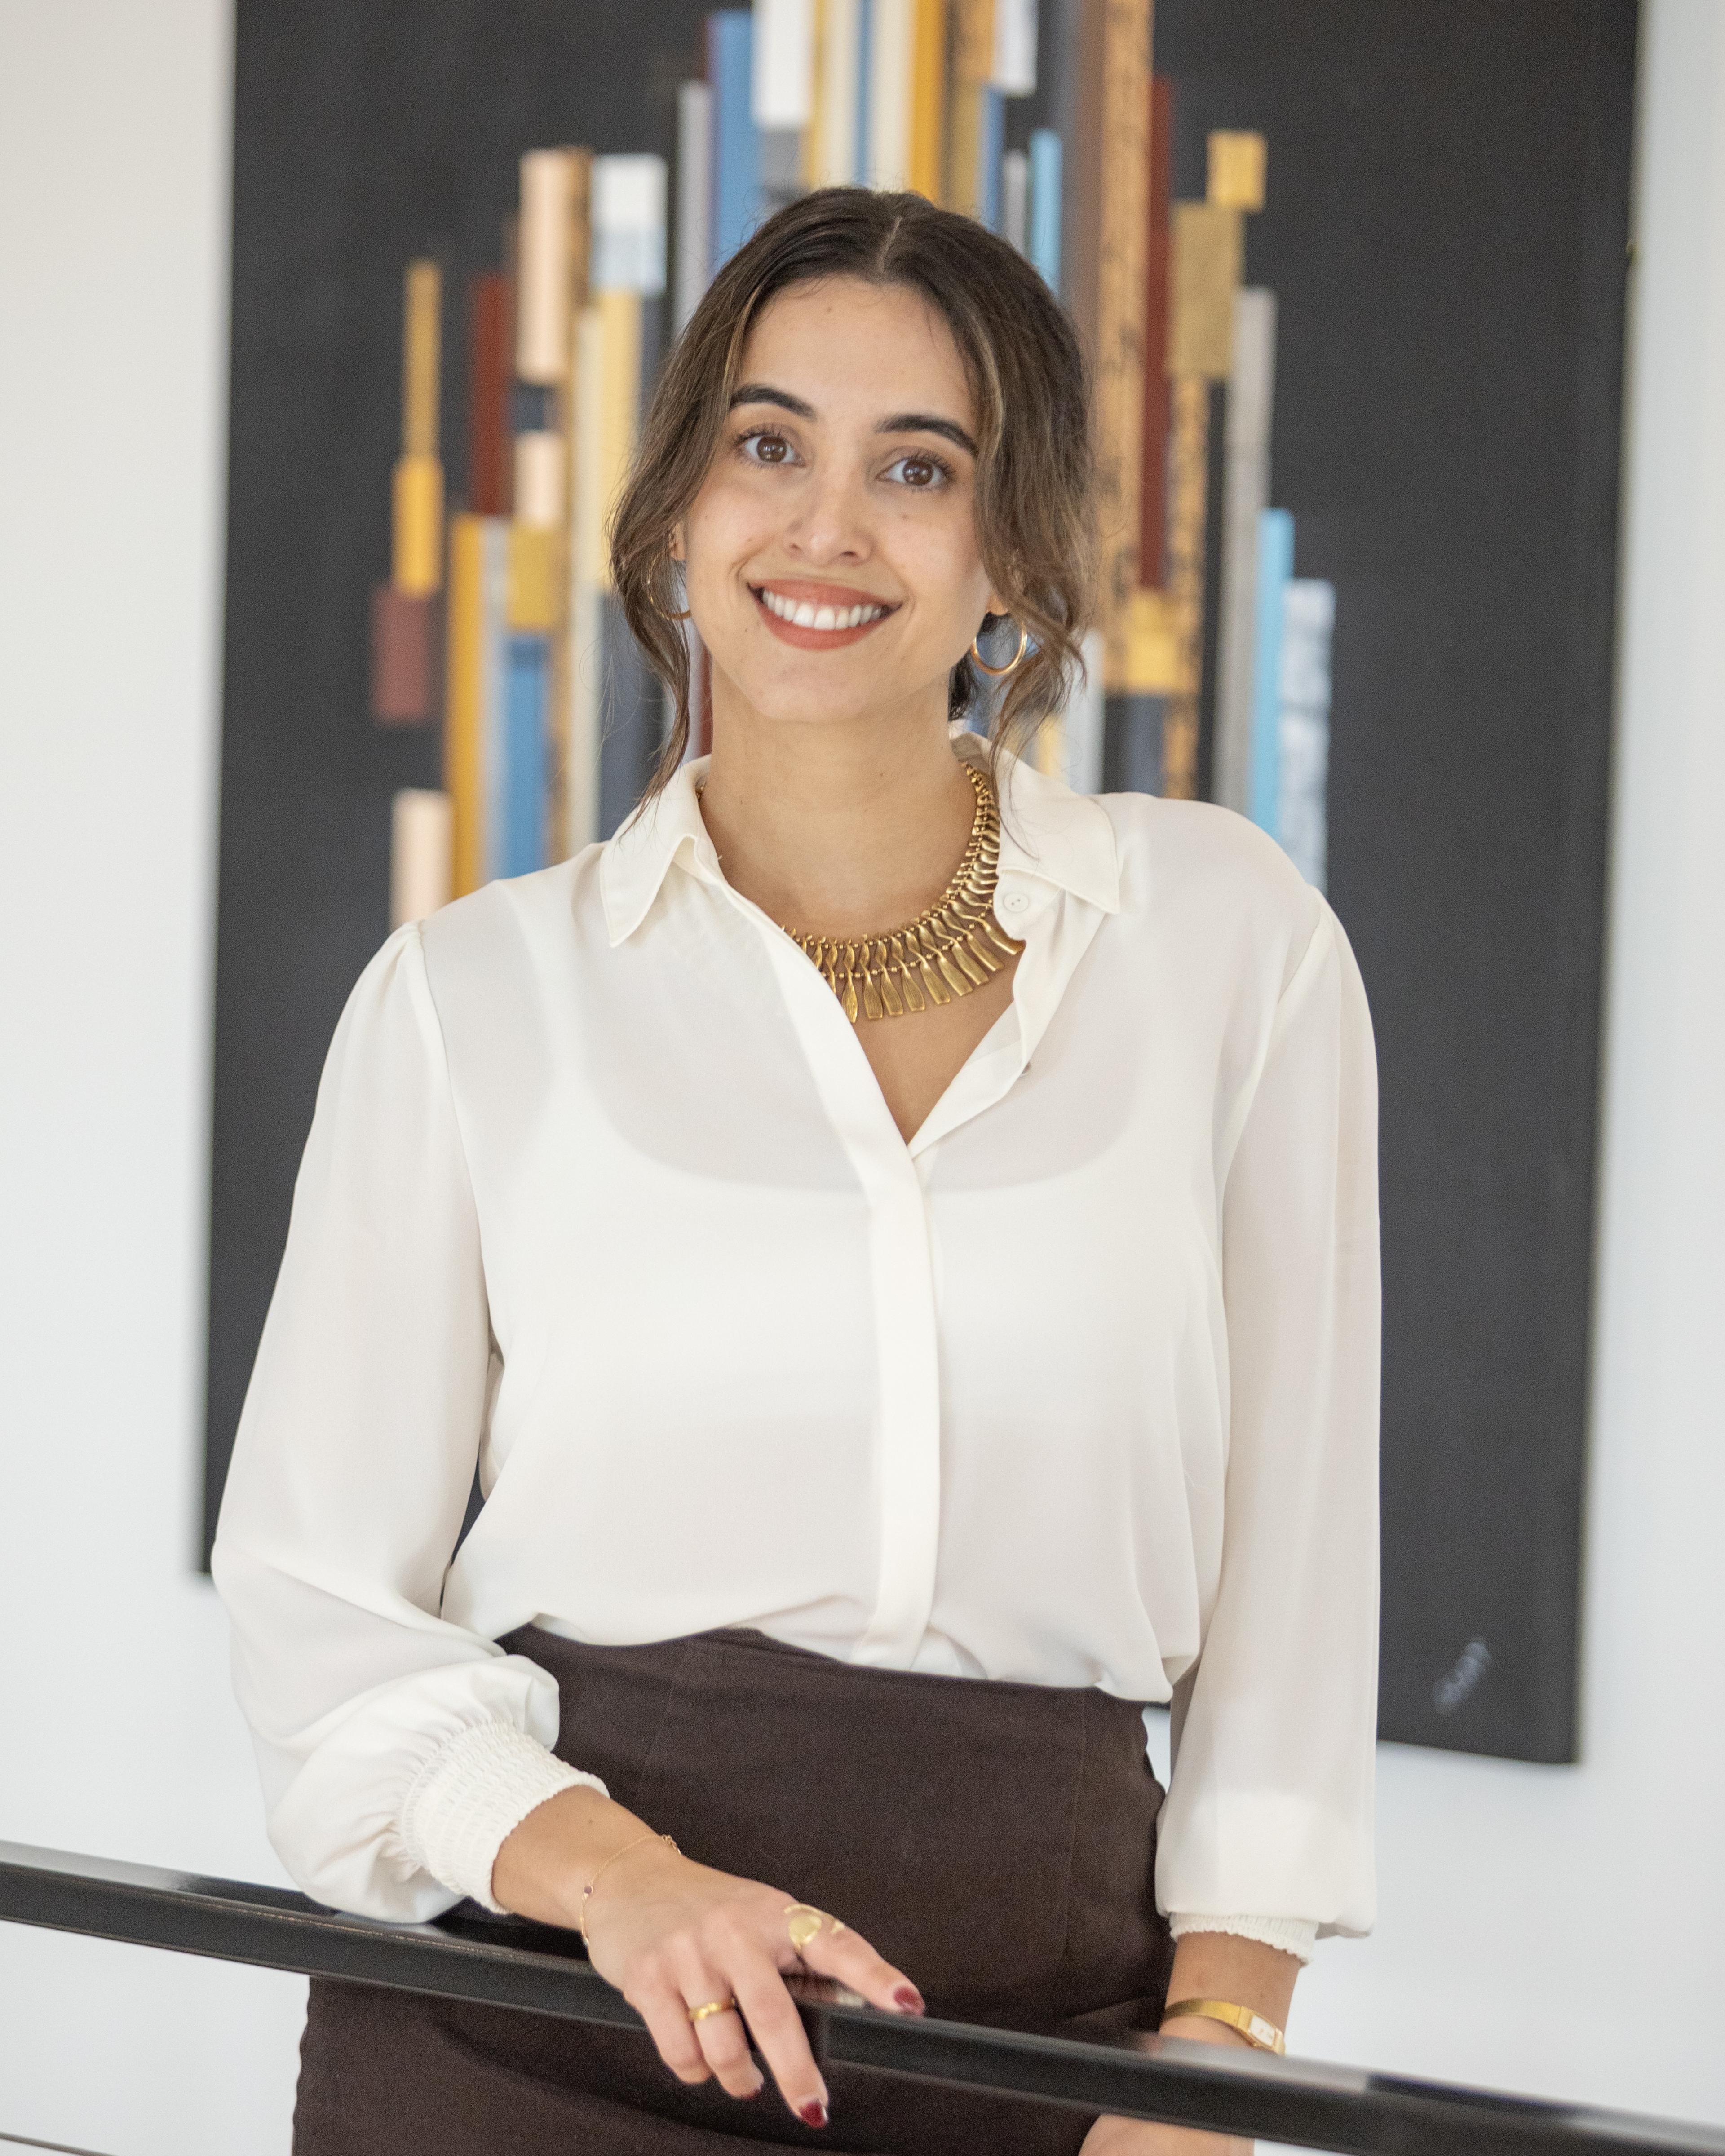
Jennifer Ferrara, Loan Officer | NMLS #2781982
Meet your lender
Behind Loans Built Like Home
I spent years working directly with mortgage lenders and brokers to get deals to the finish line, and that taught me every in and out of what it actually takes to close a deal. That is why I build every loan, with a team behind me making sure nothing gets missed, to survive underwriting the first time, so your closing date actually holds.
Direct cell, not a queue
You get my actual number on day one. Call or text, and you will reach me, not a rotation of whoever picks up.
I read a contract like an agent
Years of negotiating offers means I catch the financing terms that cause problems later, not just the credit score.
Spanish-Speaking Lender
Conversationally fluent, and I can close your loan in Spanish from start to finish if that is easier for you.
What that actually looks like
- Your realtor’s calls
- Answered directly, same day.
- Rate math
- Shown side by side, explained, never pushed.
- Your closing date
- Built backward from your contract date, so we hit the timeline you actually need.
- Eyes on your transaction
- Always watched, not just by me. My team tracks every stage alongside me, so nothing waits on one calendar.
Ready to talk through your specific situation?
Talk it through with meI specialize here because I live here.
These seven communities are where I spend my time and know the price points, the tax rates, and the loan programs that actually fit. I am licensed across Texas, so if you are buying anywhere in Central Texas, or beyond, I want to hear about it.
Service area shown for general reference only.
The ones that come up most
If yours is not here, ask me. No question about this is too small, and most of them have better answers than people expect.
Why use a broker in Texas instead of going straight to my bank?
A bank can only offer you what that bank sells. As a broker I shop your loan across more than 40 wholesale lenders, and those lenders price the same borrower differently depending on credit tier, property type, occupancy, and how their pricing looks that particular week. The spread between the best and the worst quote on an identical loan is real money over the life of the loan. It also means a loan one lender declines is often a loan another lender wants, which is the difference between hearing no and hearing yes.
Will I only be working with you, or is there a team?
I’m your one point of contact from the first call to closing, you will never be bounced between people. Behind me is a full processing team and a disclosure specialist through MPA Home Loans, so your loan keeps moving even when I am in back-to-back calls. One relationship, backed by a real team, nothing slips through.
How much does a mortgage broker make on a $500,000 mortgage in Texas?
It comes from one of two places. Either the lender pays it directly, built into that lender’s own pricing on your loan rather than added on top, or you pay it yourself as the borrower, usually structured as part of your closing costs. Federal rules do not allow both on the same loan. Which structure applies, and the exact amount, depends on the lender, the loan program, and the specifics of your loan, and it is disclosed to you in writing on your Loan Estimate before you sign anything, so you see the real number rather than a generic one. I am glad to walk through exactly how that works on your specific loan.
What credit score and down payment do I actually need to buy a home in Texas?
It depends on the loan type more than any single rule. FHA can start around a 580 score with 3.5 percent down, conventional usually wants a stronger profile but can start near 3 percent down, and there are programs built for almost every situation in between. Rather than quote a blanket minimum, tell me where you actually stand and I will tell you which programs are realistically in play.
Can I get pre-approved in Texas before I have a house picked out?
Yes, and it is the right order to do things in. Pre-approval tells you your real budget, your real payment, and the cash you actually need, before you fall for a house you have not run the numbers on. It takes looking at your income, credit, and documentation, not just a five minute form, and it is free and does not commit you to anything.
What is the difference between a mortgage broker and a mortgage lender in Texas?
A direct lender only offers you their own loan products. A mortgage broker shops your loan across multiple wholesale lenders to find the best fit. I work with more than 40 wholesale lenders, so your loan gets priced by many of them at once instead of just one, and a program that does not fit one lender’s guidelines often fits another’s. People search both terms for the same reason, they want someone who can actually get them a loan. The real question is not which word to use, it is whether that person is comparing lenders on your behalf or handing you one bank’s menu.
A second opinion on your Loan Estimate
Already have an estimate from another lender? Send me the numbers and I will tell you what looks high, what looks low, and what is missing. It costs nothing, nobody pulls your credit, and the decision stays yours.
- Rate versus APRHow much of the cost sits in fees and points instead of the rate.
- Lender fees, taxes and insuranceThe charges that are easiest to compare and the estimates that come in light.
- Cash to close, lock and timingWhat you actually bring, and what happens if the lock expires.
Please leave out your Social Security number, income, and bank information. A real comparison with real numbers from me starts with an application.
Still deciding?
Call or text if you would rather just talk it through, or grab a time on my calendar. Pick whichever of these feels easier, all of them are a normal way to start.
Nook Lending is powered by MPA Home Loans. Jennifer Ferrara, Loan Officer, NMLS #2781982. MPA Home Loans NMLS #2778343. This is not a commitment to lend. All loans are subject to credit approval, income and property verification. Rates, terms, and programs are subject to change without notice. Equal Housing Opportunity.